Student Loan Forgiveness 2026: New Eligibility & Deadlines Explored
Anúncios
Student Loan Forgiveness 2026: Navigating New Eligibility Requirements and Deadlines
The landscape of student loan debt in the United States is constantly evolving, and with it, the opportunities for borrowers to find relief through forgiveness programs. As we look towards 2026, many borrowers are wondering what the future holds for student loan forgiveness 2026. Understanding the potential changes in eligibility requirements, crucial deadlines, and available programs is paramount for anyone seeking to reduce their educational debt burden. This comprehensive guide will delve deep into the anticipated updates, offering insights and actionable advice to help you prepare.
Student loan debt has become a significant financial hurdle for millions of Americans. The sheer volume of outstanding loans, coupled with varying interest rates and repayment structures, often leaves borrowers feeling overwhelmed. In response, various federal programs have been established over the years to offer pathways to forgiveness. However, these programs are rarely static. They are frequently subject to legislative changes, administrative adjustments, and policy shifts that can profoundly impact who qualifies and under what conditions. Therefore, staying informed about the latest developments, particularly concerning student loan forgiveness 2026, is not just advisable—it’s essential.
Anúncios
The year 2026 is a critical juncture for several reasons. Policies enacted in previous years, including the aftermath of the COVID-19 pandemic and subsequent relief measures, are expected to have fully matured or undergone further revisions by then. New legislative priorities may emerge, potentially introducing entirely new programs or significantly altering existing ones. For borrowers, this means a period of both potential opportunity and uncertainty. Our aim is to equip you with the knowledge needed to navigate this complex environment effectively, ensuring you are well-prepared to seize any available opportunities for student loan forgiveness 2026.
The Current State of Student Loan Forgiveness Programs
Before we project into 2026, it’s vital to have a solid understanding of the foundational student loan forgiveness programs currently in place. These programs serve as the bedrock upon which future changes will likely be built. Familiarity with their current structure, eligibility, and common pitfalls will be invaluable as you prepare for any updates related to student loan forgiveness 2026.
Public Service Loan Forgiveness (PSLF)
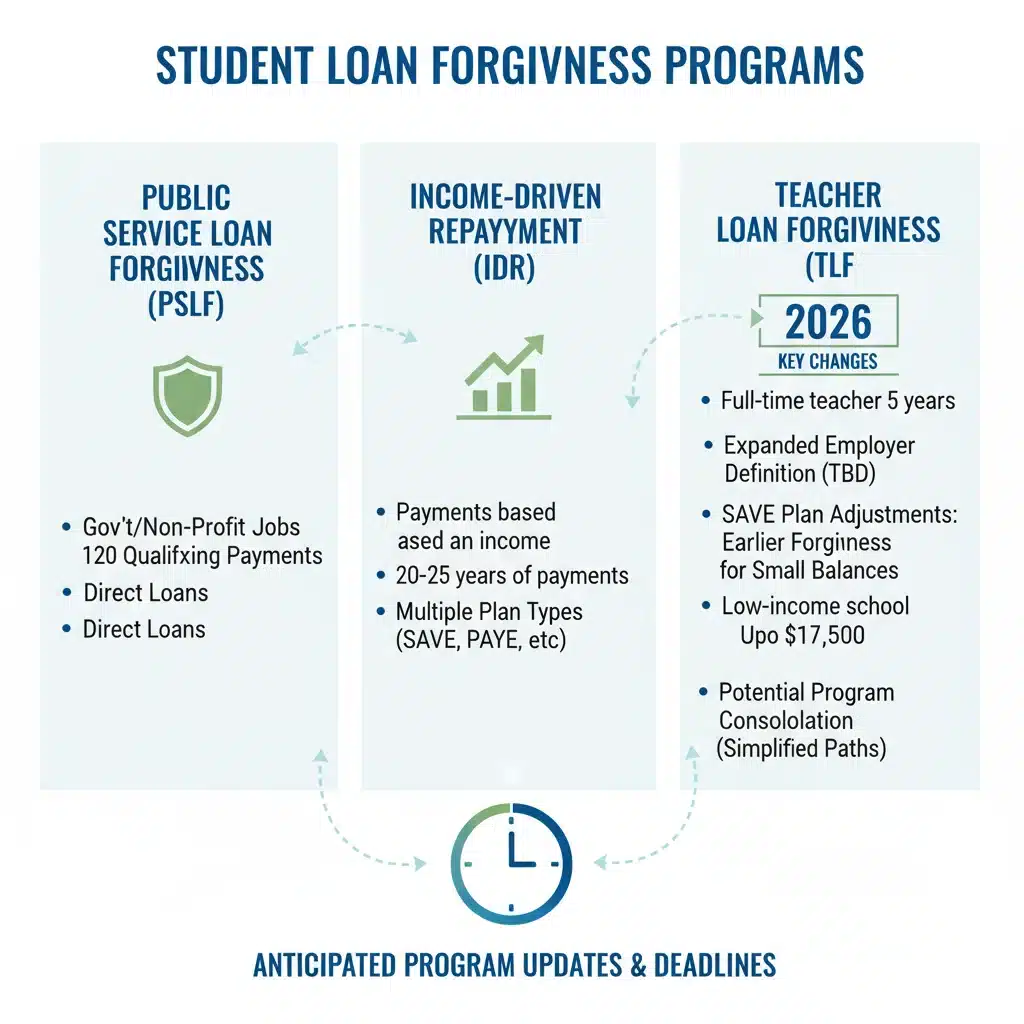
The Public Service Loan Forgiveness (PSLF) program is perhaps one of the most well-known avenues for federal student loan forgiveness. Designed to encourage individuals to enter and remain in public service, PSLF offers tax-free forgiveness of the remaining balance on Direct Loans after 120 qualifying monthly payments have been made under a qualifying repayment plan while working full-time for a qualifying employer. Qualifying employers typically include government organizations (federal, state, local, or tribal) and eligible non-profit organizations. The definition of ‘full-time’ and ‘qualifying payments’ has been a source of confusion for many borrowers, leading to historically low approval rates. However, recent temporary waivers and ongoing efforts to streamline the program suggest a commitment to improving its accessibility.
- Key Requirements: Direct Loans, 120 qualifying payments, qualifying employment, income-driven repayment plan.
- Common Challenges: Tracking payments, employer eligibility, understanding repayment plan nuances.
Income-Driven Repayment (IDR) Plan Forgiveness
Income-Driven Repayment (IDR) plans offer another pathway to forgiveness, albeit typically over a longer period. These plans cap monthly student loan payments at an affordable percentage of a borrower’s discretionary income. After 20 or 25 years of qualifying payments (depending on the specific IDR plan and whether loans are for undergraduate or graduate study), any remaining balance is forgiven. While this forgiveness is generally taxable as income, IDR plans provide a crucial safety net for borrowers with low incomes relative to their debt. The current IDR plans include Income-Based Repayment (IBR), Pay As You Earn (PAYE), Revised Pay As You Earn (REPAYE), and Income-Contingent Repayment (ICR).
- Key Requirements: Federal student loans, consistent payments for 20-25 years, annual income certification.
- Common Challenges: Forgetting to recertify income, the tax bomb on forgiven amounts, complex plan choices.
Teacher Loan Forgiveness (TLF)
The Teacher Loan Forgiveness (TLF) program is specifically designed to incentivize individuals to teach in low-income schools or educational service agencies. Eligible teachers can have up to $17,500 of their Direct Subsidized and Unsubsidized Loans and Federal Stafford Loans forgiven after completing five consecutive, complete academic years of teaching in a qualifying low-income school. The amount of forgiveness depends on the subject taught (e.g., highly qualified math or science teachers at the secondary level, or special education teachers, qualify for the higher amount).
- Key Requirements: Teach full-time for five consecutive years, qualifying school, specific loan types.
- Common Challenges: Meeting ‘highly qualified’ criteria, ensuring school eligibility, understanding loan type restrictions.
Other Forgiveness and Discharge Options
Beyond these primary programs, several other avenues for relief exist, including:
- Total and Permanent Disability (TPD) Discharge: For borrowers with a total and permanent disability.
- Borrower Defense to Repayment: For borrowers whose schools misled them or engaged in other misconduct.
- Closed School Discharge: For borrowers whose school closed while they were enrolled or shortly after they withdrew.
- Death Discharge: Federal student loans are discharged upon the death of the borrower.
Each of these programs has its own specific set of criteria and application processes. Understanding which programs you might qualify for today is the first step in preparing for any changes concerning student loan forgiveness 2026.
Anticipated Changes to Student Loan Forgiveness in 2026
Predicting the exact legislative and policy landscape for student loan forgiveness 2026 is challenging, but we can identify several key areas where changes are most likely to occur. These potential shifts could significantly impact eligibility, the amount of forgiveness, and the administrative processes involved. Keeping these possibilities in mind will help borrowers proactively plan.
Evolution of Income-Driven Repayment (IDR) Plans
One of the most significant areas of ongoing reform is the Income-Driven Repayment system. The Biden administration has already introduced significant adjustments, such as the SAVE Plan (Saving on a Valuable Education), which replaced the REPAYE plan. The SAVE Plan offers more generous terms, including lower discretionary income percentages for undergraduate loans and a provision to prevent interest capitalization as long as scheduled payments are made. It also offers a shorter path to forgiveness for borrowers with lower original loan balances.
By 2026, we could see further refinements or even entirely new IDR plans. Potential changes might include:
- Further Reduction in Discretionary Income Percentage: Making monthly payments even more affordable.
- Expanded Eligibility: Broadening the types of loans or borrowers who can access IDR benefits.
- Streamlined Application Process: Simplifying the annual income recertification and enrollment procedures.
- Addressing the ‘Tax Bomb’: Legislative action to make IDR forgiveness tax-free, similar to PSLF. This is a significant concern for many borrowers, and advocacy groups continue to push for this change.
The goal of these ongoing reforms is generally to make student loan repayment more manageable and to ensure that forgiveness programs genuinely provide relief to those who need it most. Borrowers should monitor updates from the Department of Education closely as 2026 approaches.
Potential Adjustments to PSLF Requirements
While the Public Service Loan Forgiveness program has seen significant temporary improvements, particularly through the Limited PSLF Waiver and the IDR Account Adjustment, some of these measures were temporary. By 2026, it’s possible that:
- Permanent Simplification: Some of the waiver’s beneficial provisions, such as counting previously ineligible payment periods, could be made permanent.
- Refined Employer Definitions: Clarification or expansion of what constitutes a ‘qualifying employer’ to reduce ambiguity.
- Automatic Tracking: Implementation of more robust systems for automatically tracking qualifying payments, reducing the burden on borrowers.
- Changes to Full-Time Employment: Re-evaluation of the definition of ‘full-time’ work for PSLF purposes, potentially benefiting part-time workers in public service roles.
Any permanent changes to PSLF would aim to address the historical complexities and high denial rates, making the program more accessible and effective for public servants. For those pursuing student loan forgiveness 2026 through PSLF, staying updated on these potential modifications is crucial.
New Legislation and Broader Forgiveness Initiatives
The political climate and public discourse surrounding student loan debt could also lead to new legislative initiatives. While broad-based, across-the-board student loan forgiveness has been a topic of discussion, its implementation remains politically challenging. However, by 2026, we might see:
- Targeted Forgiveness Programs: New programs aimed at specific professions (e.g., healthcare workers, STEM fields) or demographics.
- Expanded Borrower Defense: Continued efforts to provide relief to students defrauded by predatory institutions.
- State-Level Initiatives: While federal programs are central, states may also introduce or expand their own loan repayment assistance programs (LRAPs) that could complement federal efforts.
It’s important to remember that legislative processes are often slow and unpredictable. However, the consistent pressure to address student loan debt means that new programs or significant overhauls of existing ones for student loan forgiveness 2026 are always a possibility.
Eligibility Requirements for Student Loan Forgiveness in 2026: What to Expect
As programs evolve, so do their eligibility criteria. Understanding these requirements is fundamental to successfully applying for student loan forgiveness 2026. While specific details may change, certain core principles are likely to remain, alongside potential new stipulations.
Loan Type and Status
Historically, federal student loans have been the primary focus of forgiveness programs. This trend is expected to continue. Direct Loans are almost universally eligible for PSLF and IDR plans. Federal Family Education Loan (FFEL) Program loans and Perkins Loans often require consolidation into a Direct Consolidation Loan to become eligible for certain programs. Private student loans, issued by banks and private lenders, are generally not eligible for federal forgiveness programs and this is unlikely to change by 2026.
Borrowers should verify the type of their loans and consider consolidation if necessary, well in advance of any application deadlines for student loan forgiveness 2026. Keep in mind that consolidating can sometimes reset payment counts for PSLF or IDR, so careful research and advice are crucial.
Employment and Income Thresholds
For programs like PSLF and Teacher Loan Forgiveness, employment in specific sectors or types of institutions will remain a cornerstone of eligibility. For PSLF, full-time employment with a government agency or eligible non-profit is key. For TLF, teaching in a low-income school district is essential.
Income-driven repayment plans, by definition, rely on a borrower’s income relative to their family size and the federal poverty line. While the specific percentage of discretionary income used to calculate payments might change (as seen with the SAVE Plan), the principle of payments being tied to income will persist. For student loan forgiveness 2026 through IDR, annual income certification will undoubtedly remain a critical requirement.
Payment History and Duration
The number of qualifying payments is central to both PSLF (120 payments) and IDR forgiveness (20-25 years of payments). While temporary waivers have allowed certain previously ineligible payments to count, it’s uncertain if these will become permanent. Borrowers should aim to make consistent, on-time payments under a qualifying repayment plan to build their payment count. Any changes to how payments are counted, or the total number required for student loan forgiveness 2026, would be significant and widely publicized.
Residency and Other Criteria
While less common, some specialized forgiveness programs or state-specific initiatives might include residency requirements or other unique criteria. For instance, certain healthcare professional programs might require a commitment to serve in underserved areas. Staying informed about any niche programs that might emerge for student loan forgiveness 2026, particularly those relevant to your profession or location, is a smart strategy.
Crucial Deadlines for Student Loan Forgiveness in 2026
Deadlines are often the most critical, yet overlooked, aspect of student loan forgiveness. Missing a deadline can lead to forfeiture of benefits, regardless of eligibility. As we approach 2026, several types of deadlines will be paramount for borrowers to monitor.
Application Deadlines for Existing Programs
While core programs like PSLF and IDR do not typically have a single, overarching application deadline for forgiveness (applications are generally submitted once payment requirements are met), there are ongoing deadlines for:
- Annual IDR Recertification: Borrowers on IDR plans must recertify their income and family size annually. Failing to do so can lead to payment increases and interest capitalization. This will undoubtedly continue for student loan forgiveness 2026.
- PSLF Employment Certification: While not strictly a deadline, submitting the PSLF Employment Certification Form regularly (e.g., annually or whenever you change employers) is crucial for tracking progress and ensuring all payments count.
- Temporary Waivers and Adjustments: Any temporary measures, like the IDR Account Adjustment, usually have an end date. Borrowers must ensure they take action (e.g., consolidate loans) before these deadlines pass to benefit.
Potential Deadlines for New Programs or Legislative Changes
If new forgiveness programs are introduced or significant legislative changes are made, they will almost certainly come with specific application windows or cut-off dates. These could include:
- Enrollment Periods: New programs might have a limited window for borrowers to opt-in.
- Consolidation Deadlines: Certain benefits might be contingent on consolidating loans by a specific date.
- Documentation Submission: Requirements for submitting specific documentation (e.g., proof of employment, income verification) by a set date.
It’s not uncommon for these deadlines to be relatively short once announced, so staying vigilant is key for student loan forgiveness 2026.
General Financial Planning Deadlines
Beyond federal program deadlines, borrowers should also consider personal financial deadlines. These include:
- Tax Filing Deadlines: Relevant if any forgiven amount is considered taxable income.
- Budget Review Dates: Regularly reviewing your budget to ensure you can meet your monthly loan obligations.
- Credit Report Checks: Regularly checking your credit report to ensure accuracy, as student loan status impacts your credit score.
A proactive approach to managing your finances, combined with diligent monitoring of official announcements, will put you in the best position to capitalize on any opportunities for student loan forgiveness 2026.
Strategies to Maximize Your Chances for Forgiveness in 2026
Given the dynamic nature of student loan policies, a proactive and informed strategy is your best bet for maximizing your chances of achieving student loan forgiveness 2026. Here are actionable steps you can take now and in the coming years:
1. Understand Your Loan Portfolio
The first step is to know exactly what kind of loans you have. Are they federal Direct Loans, FFEL loans, Perkins Loans, or private loans? This fundamental information will dictate which forgiveness programs you might be eligible for. Log into your account on StudentAid.gov to view your federal loan history. If you have private loans, contact your loan servicer directly.
2. Stay Informed and Monitor Official Sources
Government policies can change rapidly. Do not rely solely on social media or unofficial news for updates. Regularly check official sources such as:
- The U.S. Department of Education website (StudentAid.gov)
- Your loan servicer’s website
- Reputable financial news outlets that cite official sources.
Sign up for email updates from StudentAid.gov to receive direct notifications about changes that could affect student loan forgiveness 2026.
3. Keep Meticulous Records
Documentation is key, especially for programs like PSLF. Keep records of everything:
- All loan statements
- Payment confirmations
- Employment history (for PSLF, including Employer Identification Numbers)
- Submitted forms (e.g., PSLF Employment Certification Forms, IDR applications)
- Any correspondence with your loan servicer or the Department of Education.
Having these records readily available can save you significant headaches if there are discrepancies or if you need to appeal a decision related to student loan forgiveness 2026.
4. Consider Income-Driven Repayment (IDR) Plans
If you have federal loans and are struggling with payments, or if you anticipate qualifying for PSLF or IDR forgiveness in the long term, enroll in an IDR plan. The SAVE Plan is currently the most generous for many borrowers. Remember to recertify your income and family size annually to ensure your payments remain affordable and to continue counting towards forgiveness. This is a non-negotiable step for those aiming for student loan forgiveness 2026 via IDR.
5. Explore Consolidation if Necessary
If you have older federal loans (FFEL, Perkins), you may need to consolidate them into a Direct Consolidation Loan to become eligible for PSLF or certain IDR plans. However, be cautious: consolidation can reset your payment count for PSLF or IDR. Always research the implications thoroughly or consult with a financial advisor before consolidating. The IDR Account Adjustment has provided a temporary window where consolidation might preserve past payment counts, but this window has a deadline.
6. Seek Professional Advice
Student loan regulations are complex. If you have a significant amount of debt or a complicated loan history, consider consulting with a non-profit student loan counselor or a financial advisor specializing in student debt. They can help you understand your options, assess your eligibility for current and future programs, and guide you through the application process for student loan forgiveness 2026.
7. Understand the Tax Implications
Currently, PSLF forgiveness is tax-free. However, forgiveness under most IDR plans can be considered taxable income by the IRS, often referred to as a ‘tax bomb.’ While there have been temporary legislative changes to make IDR forgiveness tax-free, this provision is not permanent. By 2026, it’s crucial to understand whether any forgiven amount will be added to your taxable income and to plan accordingly.
The Future Outlook for Student Loan Forgiveness Beyond 2026
While our focus is on student loan forgiveness 2026, it’s important to recognize that the conversation around student debt will continue. The long-term trajectory of these programs will likely be shaped by several factors:
- Economic Conditions: Recessions or periods of economic instability often spur calls for greater financial relief, including student loan forgiveness.
- Political Landscape: Changes in presidential administrations and congressional majorities can lead to significant policy shifts.
- Advocacy Efforts: Student loan borrower advocacy groups continue to push for more expansive and accessible forgiveness programs.
- Higher Education Costs: As tuition costs continue to rise, the pressure to address student debt will likely intensify, leading to ongoing discussions about forgiveness.
Borrowers should view student loan forgiveness 2026 not as a final destination, but as a point in an ongoing journey. The ability to adapt to new rules and continuously seek out information will be key to managing student debt effectively in the years to come.
Conclusion
The path to student loan forgiveness is rarely straightforward, and the outlook for student loan forgiveness 2026 is no exception. However, by understanding the current landscape, anticipating potential changes, and adopting a proactive approach, borrowers can significantly improve their chances of finding relief. Stay informed, keep meticulous records, and don’t hesitate to seek expert advice. Your financial future depends on your diligence in navigating these complex waters. The goal is not just to survive the student loan crisis, but to thrive beyond it, and strategic engagement with forgiveness programs is a powerful tool to achieve that.